Have you ever walked into a bank with a large amount of cash and expected to deposit it and leave a few minutes later? If so you might be surprised when the bank asks you a few questions and the transaction takes longer than expected.
This happens because banks have rules they must follow when handling large cash transactions. If you’re wondering whether your bank reports your deposit, whether the IRS finds out, or whether you’ve done something wrong, allow me to explain everything you should know.
Quick Answer
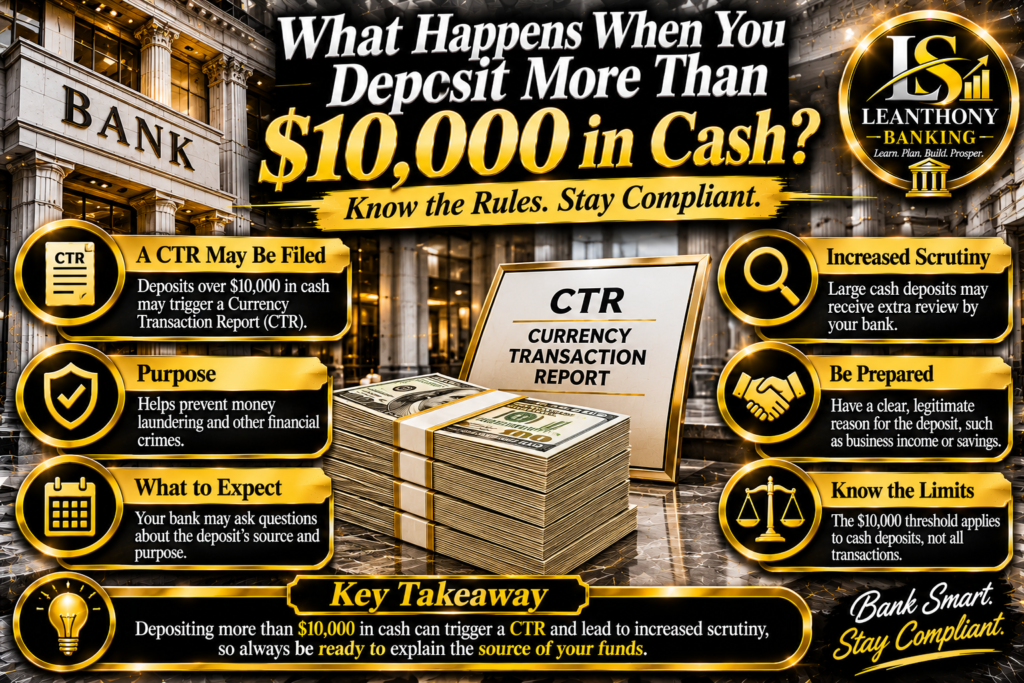
When you deposit more than $10,000 in cash, your bank generally must file a Currency Transaction Report (CTR) with the Financial Crimes Enforcement Network (FinCEN).
FinCEN is a government agency that collects financial information to help detect money laundering and other financial crimes. The IRS can access this CTR information for authorized tax purposes.
So to the question, does banks report cash deposits to IRS the answer is techincally no however the IRS can access that information.
A report doesn’t automatically mean you’re in trouble, under investigation, or required to pay taxes on the money.
What Happens When You Deposit More Than $10,000 in Cash?
When you make a cash deposit over $10,000, your bank generally has to report the transaction. You may also be asked for additional information, and the process can take longer than a regular deposit.
In my banking experience, clients sometimes expect to walk in, deposit their money, and leave within a few minutes. They sometimes then become irritated when they realize the bank needs to ask questions before completing the transaction.
I usually explain that, because of the size of the transaction, it will take a little longer and I’ll need to ask a few questions for compliance purposes.
The bank may need to verify your identity and collect information about the transaction. The exact questions and procedures can vary between banks.
You generally don’t file the CTR yourself. The bank is responsible for submitting the report when the reporting rules apply.
Does a Bank Report Cash Deposits to the IRS?
Yes and No, let me explain: banks generally send Currency Transaction Reports to FinCEN, not directly to the IRS.
FinCEN is part of the U.S. Department of the Treasury. It collects financial reports from banks and other financial institutions.
The IRS can access certain FinCEN reports, including CTRs, for authorized tax administration and enforcement purposes. So, even though your bank isn’t simply sending the deposit report straight to the IRS, the IRS may still access that information.
This is why the answer to does bank report cash deposits to IRS isn’t as simple as saying yes or no. The bank reports the transaction to FinCEN, and the IRS has authorized access to the information.
How Does the $10,000 Cash Reporting Threshold Work?
The general CTR reporting threshold is more than $10,000 in cash, not $10,000 or more.
For example:
| Cash deposit | General CTR rule |
| $5,000 | Doesn’t reach the threshold by itself |
| $10,000 | Doesn’t exceed the threshold by itself |
| $10,500 | Generally reportable |
| $15,000 | Generally reportable |
This is the basic rule behind cash deposit reporting.
One important detail: the rule applies to cash transactions, not every transaction involving more than $10,000.
A check, wire transfer, or ordinary electronic bank transfer doesn’t automatically trigger a CTR just because the amount is over $10,000.
Can Multiple Cash Deposits Be Combined?
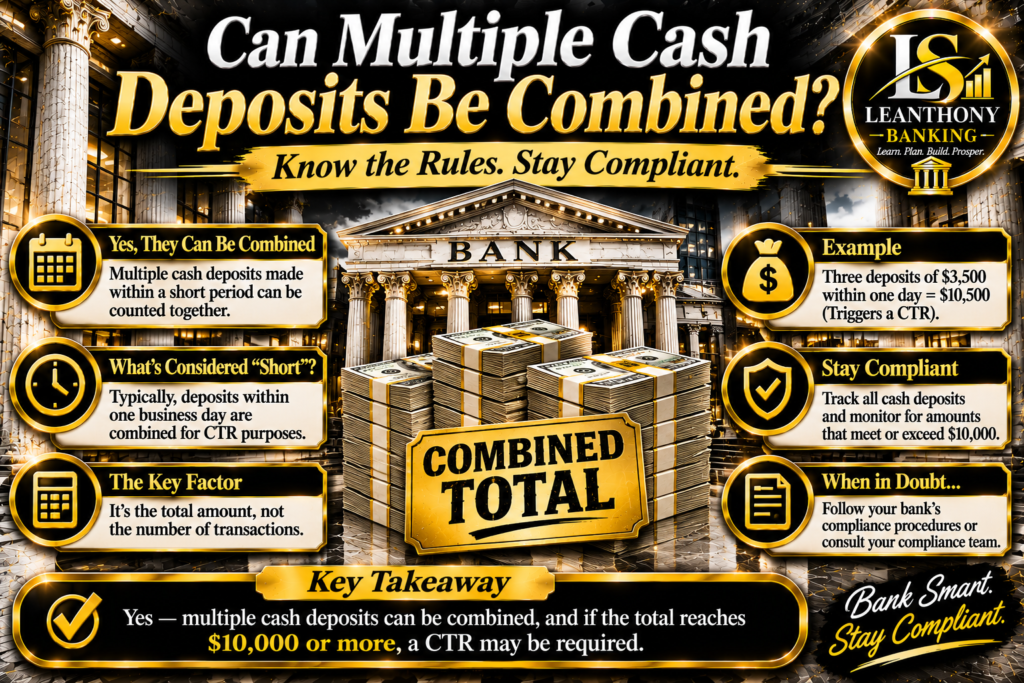
Yes. Banks may have to combine multiple cash transactions when they know the transactions were made by or on behalf of the same person during one business day.
For example, imagine someone makes two cash deposits:
| Deposit | Amount |
| Morning deposit | $6,000 |
| Afternoon deposit | $5,000 |
| Total | $11,000 |
If the bank knows both deposits were made by or on behalf of the same person, the transactions generally must be combined for reporting.
Does a Large Cash Deposit Mean You’re Being Investigated?
No.
A large cash deposit doesn’t automatically mean the bank suspects you of doing something illegal.
A CTR is a report banks generally must file when the cash reporting rules apply. This is not the bank thinking that your transaction is suspicious.
Banks also have separate rules for reporting transactions they believe may involve suspicious activity. Those reports are called Suspicious Activity Reports (SARs).
A routine CTR and a suspicious activity report are not the same thing. A large cash deposit can receive additional review, but you shouldn’t assume that filing a CTR means you’re being investigated.
Are Cash Withdrawals Reported Too?
Yes. Cash withdrawals can also trigger CTR reporting.
For example, withdrawing $12,000 in cash generally falls under the same reporting threshold as depositing $12,000.
The rules cover both money going into a bank and cash coming out. Banks consider cash deposits and withdrawals separately when determining whether the reporting threshold has been reached.
Does a Cash Deposit Mean You Owe Taxes?
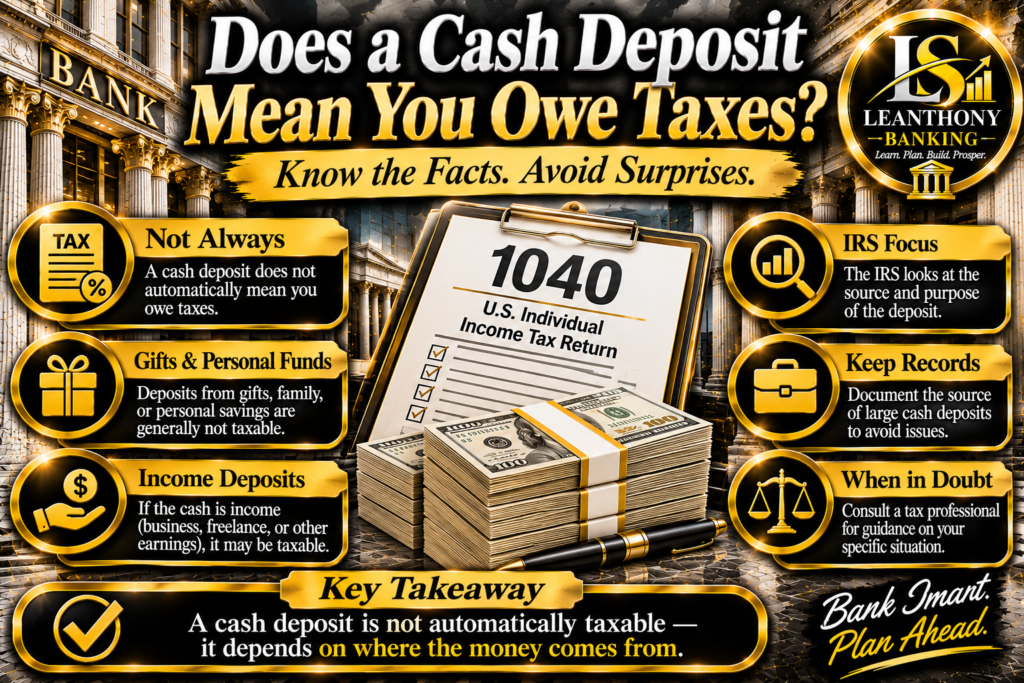
No. A cash deposit doesn’t automatically become taxable income just because the bank reports it.
What matters is where the money came from and what the money represents.
For example, depositing money from selling a personal item doesn’t automatically mean the entire deposit is taxable. The tax result may depend on whether you made a profit and the details of the sale.
A CTR is a bank reporting document, not a tax bill. If you’re unsure whether money you received is taxable, speak with a qualified tax professional.
Conclusion
So, what happens when you deposit more than $10,000 in cash? Your bank generally collects the required information and files a Currency Transaction Report with FinCEN. The IRS may access that report for authorized purposes, but the report doesn’t automatically mean you’ve done anything wrong or owe taxes.
If you’re asking does bank report cash deposits to IRS, remember the important distinction: the bank reports to FinCEN, and the IRS can access the information.
I’m Leanthony Stephens, and through Leanthony.com, I want to make banking and consumer finance easier to understand. You shouldn’t need a banking background to know what happens when you deposit your own money.
Authoritative Sources
- IRS: Bank Secrecy Act
- IRS: Currency Transaction Report Information
- FinCEN: Currency Transaction Report FAQs
- IRS: Disclosure of Bank Secrecy Act Information
Internal Linking Opportunities
Add these links when the articles are published:
- What Is a Currency Transaction Report (CTR)?
- What Is the Bank Secrecy Act?
- Difference Between CTR and BSA in Banking
- Currency Transaction Report Requirements
- CTR Filing Deadline
- Currency Transaction Report Examples
- CTR vs. SAR
- What Is a Suspicious Activity Report?